The Future of Startup Accelerators Is Virtual and Equity-Free: Rethinking Entrepreneurial Support for the Era of Solo, AI-Enabled Founders
1Mby1M Research · Research Paper
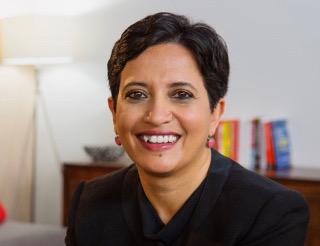
Sramana Mitra, Founder and CEO of 1Mby1M
Abstract
The global entrepreneurial landscape is currently undergoing a structural transformation characterized by significant technological shifts, persistent labor market disruption, and the emergence of non-traditional venture creation patterns. While the inaugural generation of startup accelerators was architected to serve full-time founding teams pursuing rapid venture capital (VC) financing within high-growth ecosystems, the modern entrepreneurial reality has diverged.
An increasing proportion of founders are now launching ventures while retaining professional employment, leveraging artificial intelligence (AI) to optimize productivity, and prioritizing capital-efficient, sustainable growth over immediate external fundraising.
This paper argues that these structural changes necessitate a fundamental redesign of the accelerator model.
Drawing upon contemporary research in entrepreneurial finance, labor economics, and founder ownership theory, the analysis demonstrates that traditional, equity-charging, cohort-based programs remain optimized for an era that no longer reflects the needs of the majority of founders.
We identify four foundational forces reshaping the sector: the rise of solo entrepreneurship; the maturation of “bootstrapping with a paycheck” as a dominant strategy; workforce displacement driven by technological advancements; and the escalating long-term costs of premature founder equity dilution.
Building on these insights, this paper proposes a next-generation accelerator framework defined by four distinct pillars: virtual delivery, equity-free participation, continuous engagement, and founder-centric capital preservation. By shifting the objective from maximizing fundraising velocity to maximizing customer validation, strategic flexibility, and long-term ownership, the proposed model offers a robust alternative to the venture-backed status quo. The paper concludes that the future of entrepreneurial support lies not in replicating institutional VC selection mechanisms, but in creating globally accessible, resilient learning systems capable of supporting diverse entrepreneurial trajectories.
I. Introduction: The Institutional Stasis of Accelerator Models
Startup accelerators have undoubtedly become one of the most influential institutional innovations in modern entrepreneurship. Over the past two decades, thousands of these programs have emerged globally, operating under the shared premise that they could successfully transform early-stage ventures into scalable entities through a potent combination of mentorship, structured education, investor introductions, and access to elite networks. Their influence has been foundational, shaping entrepreneurial norms, setting founder expectations, and defining the characteristics of “successful” innovation ecosystems across both developed and emerging markets.
However, the traditional accelerator model was largely forged during a specific macroeconomic period in a specific geography (Silicon Valley): one characterized by abundant, low-cost venture capital, relatively predictable labor markets, and a pervasive, almost dogmatic assumption that venture-scale growth represented the only legitimate trajectory for technology startups. In this environment, an accelerator’s success was inextricably linked to fundraising outcomes, the production of unicorns, and the ability to integrate startups into the venture capital pipeline.
Recent empirical and market evidence suggests that this foundational environment has shifted substantially. Venture capital markets have become increasingly selective following the post-2021 repricing of private technology assets. Simultaneously, the proliferation of cloud computing, no-code development, and, most significantly, generative artificial intelligence has lowered the barriers to entrepreneurship while fundamentally altering the profile of the typical founder. We are witnessing a transition where increasing numbers of entrepreneurs are launching ventures while remaining employed, operating as solo entities, or deliberately pursuing capital-efficient, customer-funded business models long before – or even in lieu of – considering external institutional financing.
These structural shifts raise a critical question of institutional relevance: Are existing startup accelerator models still optimized for the entrepreneurs they seek to serve?
This paper contends that the answer is increasingly negative. The traditional accelerator model, characterized by its reliance on fixed-duration, in-person cohorts and the exchange of equity for service, reflects assumptions about entrepreneurship that are rooted in an earlier phase of the venture industry. While these physical programs remain effective for a specific subset of high-growth ventures, they are structurally ill-suited to the rapidly growing population of founders pursuing flexible venture development and “bootstrapping with a paycheck”.
The institutional inertia maintaining these legacy models obscures a broader truth: entrepreneurial ecosystems have become significantly more heterogeneous than the institutions designed to support them. Consequently, the accelerator of the future must evolve from a venture-capital gateway into a flexible, educational platform – one that respects the economic realities of the age of artificial intelligence. This paper explores how such a framework – virtual, equity-free, and globally accessible – not only democratizes access to entrepreneurial education but also fundamentally improves the probability of long-term venture survival and value creation.
II. Theoretical Foundations: Agency, Signaling, and the Cost of Capital
The persistence of the traditional startup accelerator model – characterized by physical, equity-charging cohorts – cannot be explained by market efficiency alone. Instead, it is the result of path dependency and a legacy reliance on theories of venture financing that are increasingly decoupled from the modern economic reality. To understand why the next generation of accelerators must be virtual and equity-free, we must first deconstruct the theoretical pillars that sustained their predecessors: signaling, agency theory, and the strategic value of founder optionality.
Signaling Theory in Startup Finance
Historically, startup accelerators functioned as critical institutional intermediaries that resolved “information asymmetry” – the fundamental economic problem wherein founders possess private information about venture quality that investors lack.
In the early 2000s, when venture capital markets were less transparent, accelerators provided a “quality seal” or certification. By selecting a small cohort from a vast applicant pool, accelerators signaled to the venture capital market that a venture had been vetted, thereby reducing the due diligence burden for follow-on investors.
However, the “signaling value” of this traditional model has experienced a precipitous decline in the age of global connectivity and AI-enabled due diligence. We are currently witnessing a shift from human-mediated certification to data-mediated verification.
When market data, customer traction, and product-market fit metrics are globally accessible via digital platforms, the signaling benefit of a localized, three-month cohort diminishes.
In this new environment, the support by a physical accelerator is increasingly redundant, as digital reputation systems and automated performance tracking provide a more accurate, high-fidelity signal of venture viability than a demo day. Accelerators that rely solely on their status as gatekeepers are essentially selling a service – the “signal” – for which the market has already provided a more efficient, digital substitute.
The Agency Cost of Early Equity
A critical, often overlooked aspect of the traditional accelerator model is the “Equity Tax” – the agency cost imposed on founders when they exchange ownership for participation at the earliest, most uncertain stages of company formation. In agency theory, the accelerator acts as an agent that is often incentivized to optimize for the investor’s objectives – namely, high-velocity exits and unicorn-scale valuation — rather than the founder’s objectives, which may include long-term profitability, sustainable growth, or a smaller, earlier exit leading to quicker founder wealth creation.
The economic impact of this early-stage dilution is compounded by the mathematical reality of venture financing. A founder’s total equity retention is not static; it is subject to a decaying progression over the venture’s lifecycle.
When this extraction occurs before the business has established repeatable revenue or verified market demand, the cost is disproportionately high. By taking equity early, accelerators reduce the founder’s base ownership, which effectively increases the “cost” of every subsequent round of dilution. It also takes away the flounder’s flexibility to pivot when things are not quite hitting stride.
This misalignment creates an agency problem where the accelerator’s interests are tied to the investor’s need for equity, rather than the founder’s need for capital efficiency. Programs that demand equity for mentorship effectively extract a premium on the founder’s future upside while providing only a depreciating educational utility.
The consequences of failing to prioritize early-stage equity preservation extend beyond mere financial loss; it creates the structural vulnerability of the ‘Zombie Startup.’
A Zombie Startup is a venture that has achieved a high, often artificial, valuation through aggressive capital absorption but lacks a viable, self-sustaining business model.
These entities are trapped in a perpetual cycle of needing external funding to survive, as their operational costs and growth targets are tethered to investor-driven expectations rather than genuine customer demand. VCs require startups to go from 0 to $100M in 5-7 years, and in the AI era, they want these targets to be achieved in 3-5 years.
When founders surrender substantial equity early – often under the guise of ‘accelerated’ growth – they lose the strategic sovereignty required to pivot toward profitability when the business fails to deliver the velocity level that investors demand.
Consequently, they become captives of a ‘growth-at-all-costs’ mandate, unable to exit, and unable to raise further financing because of the lack of velocity.
At this point, even if they are a profitable $50M Annual Recurring Revenue (ARR) business, they are stuck in a cap table and equity structure that prevents them from exiting profitably. They can keep going, but are effectively stuck in a no man’s land with no path to liquidity or wealth creation.
This is what is called a “Zombie Startup.” In cases where startups raised funding at billion dollar valuations but failed to deliver a high velocity business, they are called “Zombie Unicorns.”
By emphasizing equity preservation from the outset, founders ensure they maintain the optionality to build a resilient, profitable enterprise rather than a hollow, venture-dependent entity that lacks the autonomy to survive a slower growth trajectory.
Contrast this with a bootstrapped business that preserves founder agency and autonomy. Even if their growth is linear and not exponential, the business needs to feel no external pressure to exit or raise funding. It can, potentially, exit at a modest valuation, or keep going as a profitably, sustainable, long term business. Thus, it is not a zombie.
Our premise is that a zombie outcome is not a desirable one for startups. Yet, nine out of ten VC funded startups either end up dead or become a zombie.
And the startup accelerators of the world have become factories of producing zombie startups en masse.
Optionality as an Asset
The most profound, yet under-theorized, loss associated with traditional accelerator participation is the erosion of “Founder Optionality.” In financial economics, optionality is the right, but not the obligation, to take a specific action in the future. For a startup founder, optionality is the ability to choose between multiple paths: bootstrapping to profitability, delaying fundraising until bargaining power is maximized, pivoting into a new market, or accepting a smaller acquisition offer.
When founders surrender early equity, they are not merely giving up a percentage of their company; they are surrendering their strategic sovereignty. As founder ownership declines, the discretion required to make decisions that prioritize long-term value over short-term investor demands also decreases.
Conversely, in a virtual, equity-free model, the founder preserves their optionality. By financing development through customer revenue or personal income – often referred to as “bootstrapping with a paycheck” – the founder maintains the ability to dictate the venture’s trajectory. Preserving equity is therefore not merely a defensive tactic to protect wealth; it is a proactive strategy to maintain the agility required to survive and thrive in a volatile, AI-driven economy.
III. The Macro-Labor Shift: The Rise of the “Autonomous Builder”
The shift in accelerator design is not merely an institutional trend; it is a downstream reaction to a fundamental, structural transformation in the global labor market. The historical archetype of the entrepreneur – a full-time founder who abandons salaried employment to pursue a venture-backed unicorn quest – is being superseded by the “Autonomous Builder.” This evolution is driven by the convergence of artificial intelligence, persistent labor market volatility, and the democratization of digital infrastructure.
The AI Disruption Thesis: Productivity and the Minimum Efficient Scale
Artificial intelligence serves as a critical multiplier that has fundamentally shifted the “minimum efficient scale” required to launch a competitive business. Historically, the requirement for a “founding team” was predicated on the need for complementary human capital – typically a technical co-founder to build the product and a business co-founder to secure capital. The cost of coordination within these teams was high, but necessary to overcome the resource intensity of early software and product development.
AI has effectively “unbundled” these roles. Generative AI, no-code development platforms, and cloud-based infrastructure now allow a single individual to execute tasks that previously required a team of specialized employees, including software development, digital marketing, financial analysis, and content creation.
Consequently, solo entrepreneurship is shifting from a necessity born of resource constraint to a deliberate strategic choice. The autonomous builder optimizes for operational simplicity and agility, deliberately delaying organizational complexity until business fundamentals – such as repeatable revenue and verified demand – justify the overhead of an expanding headcount.
The “Career Lifeboat” and the Economics of Resilience
Parallel to these technological shifts, broader labor market dynamics have introduced a new paradigm of employment uncertainty. As technological change and organizational restructuring disrupt administrative, professional, and knowledge-intensive sectors, individuals are increasingly viewing entrepreneurship not as an alternative to a career, but as a mechanism for professional adaptation.
This has given rise to the “Career Lifeboat” framework – a strategy where individuals build and validate ventures while maintaining the security of professional employment. Conventional accelerator models often categorize this behavior as a lack of “entrepreneurial commitment”. However, from an economic standpoint, “Bootstrapping with a Paycheck” is a superior strategy for managing early-stage venture risk. By maintaining a steady income, the founder:
- Reduces personal financial vulnerability during the most volatile phase of venture formation.
- Eliminates the pressure to pursue premature venture capital, thereby preserving equity and strategic optionality.
- Allows for iterative product development based on real-world customer feedback rather than the arbitrary constraints of an investor-mandated schedule.
Far from being a sign of half-heartedness, retaining employment is an exercise in capital efficiency. It enables the founder to finance innovation using personal liquidity, ensuring that when external capital is eventually sought, it is used to accelerate a proven model rather than to subsidize unvalidated experimentation.
Structural Displacement and Necessity Entrepreneurship
While researchers continue to debate the net long-term employment effects of artificial intelligence, the short-term impact is clear: widespread structural displacement. As corporations reduce overhead and reorganize, the supply of highly skilled, industry-experienced talent entering the entrepreneurial ecosystem has increased significantly.
Many of these displaced professionals possess deep domain expertise but lack the specialized training required to navigate venture capital markets. Their immediate priority is not to secure institutional financing for an unproven concept, but to validate commercial opportunities and generate early cash flow.
Traditional, cohort-based accelerators, which often demand full-time, physical participation and an equity stake, are inherently misaligned with the needs of this demographic. These professionals cannot – and should not – sacrifice their financial resilience for a program that mandates relocation or career suspension.
Challenging the Founding Team Dogma
The emphasis on “founding teams” within traditional venture capital ecosystems has created an institutional bias that ignores the increasing effectiveness of individual founders. By prioritizing team-based ventures, the legacy accelerator model inadvertently excludes the most productive, AI-enabled solo builders who are currently redefining the economics of venture creation.
The next generation of accelerators must reconcile with the reality that the “team-first” model is no longer the unique prerequisite for scale. As digital tools continue to augment individual output, the most successful ventures of the next decade may not be those with the largest founding teams, but those with the highest degree of “founder leverage” – the ability to scale value generation without the linear scaling of headcount or capital. Institutional support systems that fail to adapt to this shift – by maintaining rigid, team-oriented, and equity-demanding structures – risk becoming irrelevant to the very cohort that will drive the next wave of innovation.
IV. The Four Pillars of the Future Accelerator
The evidence presented in the preceding sections indicates that the traditional accelerator model – reliant on physical presence, early equity extraction, and team-based cohorts – is experiencing diminishing marginal returns in the current economic landscape. To remain relevant and effective, next-generation accelerators must undergo a fundamental institutional redesign. This framework is built upon four integrated pillars: virtual delivery, equity-free participation, the explicit support of solo entrepreneurs, and the validation of “bootstrapping with a paycheck” as a primary venture strategy.
1. Virtual Delivery: The Decentralization of Entrepreneurial Talent
The legacy “Hub-and-Spoke” model of acceleration, which requires founders to relocate to specific geographic centers, is increasingly incompatible with the realities of the modern global economy. The future of acceleration must be “virtual by default,” leveraging digital collaboration, cloud infrastructure, and AI-enabled education to remove the geographic barriers that have historically limited participation.
Virtual delivery is not merely a remote adaptation of physical programming; it is a structural redesign of the learning experience. By decoupling mentorship from physical location, accelerators can democratize access for founders in secondary cities, rural regions, and emerging innovation ecosystems who would otherwise remain excluded.
Furthermore, virtual platforms allow for continuous, asynchronous engagement, enabling founders to access specialized expertise as specific operational challenges arise, rather than being confined to the rigid, time-compressed schedules of traditional three-month cohorts.
This model significantly lowers the overhead for the accelerator, allowing for greater scalability and a broader reach, while ensuring that founders can remain embedded within their local markets and connected to their immediate customer base.
2. Equity-Free Participation: Aligning Incentives through Pedagogy
The practice of extracting equity at the earliest, most uncertain stages of venture formation is one of the most significant points of friction in the traditional accelerator model. To prioritize the long-term strategic optionality of the founder, the next generation of accelerators must transition to an equity-free participation model.
This decoupling of educational support from financing decisions is essential.
By separating mentorship from equity acquisition, accelerators can align their incentives with the founder’s objectives rather than the investor’s exit requirements. An equity-free program allows founders to postpone significant dilution until they possess robust evidence of product-market fit, repeatable revenue, and commercial viability. This ensures that when the founder eventually does raise institutional capital, they do so from a position of bargaining strength, rather than out of necessity. The primary value proposition of the accelerator should be its educational pedagogy and network, not its role as an early-stage investor.
3. The Solo Entrepreneur: Embracing the New Standard
Traditional accelerator models have long harbored a “team-first” bias, viewing solo founders as exceptions to the rule. This reflects an outdated assumption that successful scaling necessitates large founding teams. In the age of artificial intelligence, this dogma must be discarded.
Advances in generative AI, automated business processes, and outsourced specialized services have dramatically expanded the productivity of the individual builder. Tasks that previously required multiple full-time employees – software architecture, customer support, content creation, and financial management – can now be executed by a single founder with the assistance of AI-driven tools.
Consequently, the solo entrepreneur is emerging as a potent force in the innovation ecosystem. Future accelerators must be specifically designed to support the solo founder, providing resources that emphasize operational simplicity, personal productivity, and the leveraging of AI to replace the overhead of a large team. Recognizing the solo entrepreneur is not an accommodation; it is an acknowledgement of the new economics of venture creation.
4. Bootstrapping with a Paycheck: Professionalizing Resilience
Perhaps the most significant shift in entrepreneurial strategy is the normalization of “bootstrapping with a paycheck” – the practice of launching a business while maintaining stable professional employment. Legacy accelerator programs often stigmatized this approach, viewing external employment as a lack of focus or commitment. The next-generation accelerator must treat this strategy as a rational, highly effective pathway to long-term success.
Maintaining a paycheck during the customer discovery and validation phase serves as a critical strategic asset. It reduces personal financial risk, provides the stability required to iterate on the product without the desperate pressure of premature fundraising, and allows the founder to build a business on the foundation of customer-funded growth rather than venture capital. This approach is not a rejection of external financing; it is a discipline that ensures founders enter the capital markets only when their business model is validated and resilient.
By explicitly supporting “bootstrapping with a paycheck,” accelerators can help a much wider demographic of professionals – who possess deep industry expertise but cannot afford to abandon their salaries – to enter the entrepreneurial ecosystem and contribute to sustained economic value creation.
V. Empirical Synthesis: The 1Mby1M Framework
To understand the practical application of the theoretical shifts proposed in this paper, it is necessary to examine One Million by One Million (1Mby1M), the first global virtual accelerator that has served as an empirical proof-of-concept for the equity-free, capital-efficient, and virtual-first paradigm since its inception.
Founded in 2010 by the author of this paper, Sramana Mitra, – a Silicon Valley-based technology entrepreneur, strategy consultant, and MIT alumna – 1Mby1M was established with the ambitious mission of helping one million entrepreneurs globally reach $1 million in annual revenue and beyond.
Unlike traditional accelerators that emerged during the “blitzscaling” era of the 2010s, we have built 1Mby1M on the contrarian philosophy that entrepreneurship should prioritize the creation of real, scalable businesses over the pursuit of early-stage venture capital.
By decoupling mentorship from the immediate requirement of equity extraction, we have operationalized a framework that challenges the industry-standard “accelerator-to-VC” conveyor belt, providing a longitudinal look at the efficacy of revenue-first growth.
The following analysis synthesizes how this methodology demonstrates that virtual, equity-free models are not only viable but superior for the modern entrepreneur.
The Operationalization of Capital Efficiency
The core innovation of the 1Mby1M framework is its rejection of the “valuation-at-all-costs” mentality in favor of capital efficiency. Rather than pushing founders toward immediate, dilutive venture financing, the methodology mandates a sequencing strategy where revenue validation precedes institutional capital.
This ensures that when a venture eventually pursues external financing, it does so with established market demand, thereby mitigating the risk of business failure and preserving founder equity. This framework operationalizes the “bootstrapping with a paycheck” strategy, providing a structured environment where founders can iterate on their business models while maintaining professional and financial resilience.
Virtual Architecture and Global Accessibility
1Mby1M demonstrates that the “cohort-based” physical model is an unnecessary constraint on entrepreneurial development. By functioning as a global virtual accelerator, the platform removes the geographic and logistical friction of traditional programs, allowing for continuous, rather than time-bound, enrollment.
This virtual-first architecture enables the inclusion of a diverse, global cohort of founders – from those in emerging markets to displaced professionals in established hubs – who are effectively supported through digital mentorship and data-driven strategic guidance. The success of this model confirms that the “innovation hub” is no longer a physical location, but a digital network of high-caliber expertise.
Founder-Centric Scaling vs. Investor-Centric Growth
A critical differentiator in the 1Mby1M framework is its alignment with the founder’s long-term interests rather than the venture capitalist’s exit timeline. Traditional accelerators often create an “accelerator-to-VC” conveyor belt that can trap founders in a cycle of dependency on continuous external funding.
In contrast, the 1Mby1M methodology emphasizes the development of “micro-multinationals” – businesses that achieve high revenue and profitability, often without the need for traditional venture capital, or by utilizing it only when necessary to scale an already proven model.
This paradigm shift moves the definition of “success” from the binary outcome of an “exit” (IPO or acquisition) to the sustained creation of economic value. By equipping founders with the strategic frameworks for revenue-first growth, the methodology ensures that entrepreneurs maintain control over their ventures, thereby retaining the strategic flexibility to navigate market volatility.
Validating the Future Paradigm
The empirical results of the 1Mby1M methodology underscore the necessity of the transition toward educational-platform-based acceleration. It serves as a longitudinal study, showing that when founders are provided with rigorous, data-driven mentorship and are liberated from the pressure of premature equity extraction, they build more resilient, profitable, and enduring businesses.
As the labor market continues to shift toward autonomous, AI-enabled roles, this framework provides the blueprint for the next generation of entrepreneurial infrastructure – one that is durable, scalable, and fundamentally founder-centric.
VI. Future Research & Policy Implications
The transition toward virtual, equity-free accelerators necessitates a parallel evolution in how we measure success and how public policy is deployed to support regional innovation.
The legacy reliance on “exit multiples” – the valuation achieved upon acquisition or IPO – is an insufficient metric for an ecosystem that increasingly prioritizes founder-centric value creation and capital efficiency. Future research and policy must shift toward metrics that capture the long-term health of the ecosystem rather than the lottery-like outcomes of a select few ventures.
Redefining Accelerator Efficacy
The academic and practitioner communities must move beyond “Capital Raised” as the primary proxy for accelerator effectiveness. This metric is fundamentally flawed, as it confuses input (the acquisition of external capital) with output (the creation of economic value). To gain a higher-fidelity understanding of accelerator efficacy, future research should prioritize the following metrics:
- Founder Net Worth Growth: Evaluating the degree to which an accelerator program protects and grows the founder’s personal equity stake throughout the venture’s lifecycle.
- Cumulative Business Profitability: Tracking the venture’s ability to generate self-sustaining cash flow, which provides a more robust indicator of long-term viability than total venture capital absorption.
- Founder Optionality Retention: Assessing the degree to which an accelerator’s terms allow founders to maintain strategic sovereignty – such as the ability to refuse unfavorable terms or pivot the business model without investor interference.
Policy Redirection: Infrastructure vs. Real Estate
Governments and economic development agencies currently allocate significant funding toward physical incubators and accelerators, often subsidizing high-cost real estate in the hope that it will stimulate local innovation. This “physical-centric” policy is increasingly outdated.
Policymakers should instead reallocate these funds toward virtual infrastructure. This includes:
- Digital Accessibility Grants: Funding high-speed digital connectivity and virtual mentorship platforms that allow talent in secondary cities and rural areas to access the same educational resources as those in top-tier hubs.
- Educational Subsidies: Supporting the creation of equity-free, virtual educational programs that provide founders with “mini-MBAs” in entrepreneurship, focusing on capital efficiency, AI productivity, and lean startup methodologies.
- Decentralized Support Systems: Encouraging the development of regional “nodes” – distributed networks of expertise that connect founders to global mentors, rather than forcing talent to migrate to a singular, congested metropolitan hub.
The Future Research Agenda
For academic researchers, the shift toward virtual and equity-free models presents a fertile ground for new inquiry. We propose three immediate areas of study:
- The Longitudinal Impact of Equity Preservation: A comparative study tracking the 10-year growth trajectories of founders who participated in equity-free programs versus those who underwent early-stage dilution.
- Autonomous Builder Productivity: Research into how AI-driven tools influence the “time-to-revenue” for solo entrepreneurs, compared to traditional team-based startups.
- Cross-Regional Ecosystem Velocity: Investigating whether virtual accelerators increase the “velocity” of innovation – the speed at which ideas transform into profitable businesses – within non-traditional geographic regions.
Conclusion of Policy Framework
The role of the state should not be to pick “winners” through venture capital intervention, but to build the educational and digital infrastructure that allows all founders to compete. By transitioning from a model that subsidizes the “winners” of the VC lottery to one that provides the foundational education for the modern “Autonomous Builder,” policymakers can create a more resilient, diverse, and robust economy.
VII. Conclusion: Architecting the Future of Entrepreneurial Support
The current state of the startup accelerator ecosystem represents a distinct example of institutional inertia – a system designed for a bygone era of capital abundance and centralized, team-based innovation that now struggles to reconcile with the decentralized, AI-empowered reality of the modern founder.
As this paper has demonstrated, the structural pillars of the legacy model – physical cohort requirements, premature equity extraction, and team-centric biases – are increasingly misaligned with the economic realities facing entrepreneurs today.
The emergence of the “Autonomous Builder” – a solo entrepreneur leveraging AI to achieve outcomes previously reserved for large teams – is not a fleeting trend but the defining characteristic of the new entrepreneurial paradigm. Coupled with labor market volatility and the rise of “bootstrapping with a paycheck,” this evolution renders traditional accelerators less like supportive institutions and more like exclusionary gatekeepers.
The “Accelerator Paradox,” where the entities meant to foster disruption remain the most resistant to it, must be resolved by a fundamental pivot toward virtual, equity-free, and founder-centric platforms.
The 1Mby1M methodology provides a blueprint for this transition, offering an empirical case study in the efficacy of virtual mentorship, revenue-first growth, and the preservation of founder optionality. This framework suggests that the future of acceleration lies not in becoming a “mini-VC” firm, but in serving as a durable, global educational institution.
By decoupling educational support from equity acquisition, accelerators can align their incentives with the long-term health of the ventures they support, fostering a generation of sustainable, capital-efficient, and resilient businesses. Ultimately, the transformation proposed herein is about maturation.
The startup ecosystem is shifting from the “Industrial Phase” of venture creation – characterized by high-risk experimentation, heavy reliance on external capital, and significant founder dilution – to the “Platform Phase,” where AI-enabled founders can rapidly prototype, validate, and scale businesses with unprecedented autonomy.
This shift does not diminish the need for mentorship or structured guidance; rather, it elevates these services to a foundational status, akin to public infrastructure.
As policymakers, investors, and educators look toward the future, the mandate is clear: we must stop subsidizing the legacy of the past and start architecting the systems of the future.
The next generation of accelerators will be defined by their ability to democratize access to world-class expertise, empower the individual builder, and champion the logic of capital efficiency. By embracing this evolution, we can move beyond the “unicorn-or-bust” narrative and build a more inclusive, diverse, and robust global economy where entrepreneurial success is determined by the founder’s capacity to create value, not by the institutional pedigree of their early-stage backers.
This is the dawn of the Platform Phase of entrepreneurship. It is time for our institutions to catch up.
VIII. References
The following bibliography synthesizes the core literature regarding venture contracting, entrepreneurial finance, and the evolution of startup accelerators.
1. Venture Contracting & Startup Accelerators
- Assenova, V. A., & Amit, R. (2024). Poised for Growth: Exploring the Relationship Between Accelerator Program Design and Startup Performance.
- Chowdhury, F., & Audretsch, D. B. (2024). Paradoxes of Accelerator Programs and New Venture Performance.
- Seitz, N., Buratti, M., Lehmann, E. E., & Kurrle, J. (2026). A Meta-analysis Towards the Effectiveness of Startup Accelerators.
2. Venture Capital, Founder Ownership & Financing
- Ang, J. S. (2007). Agency Costs and Ownership Structure.
- Noam Wasserman (2008) “The Founder’s Dilemma”
- Kaplan, S. N., & Strömberg, P. (2024). Financial Contracting Theory Meets the Real World: An Empirical Analysis of Venture Capital Contracts
- Roizen, H. (2022). You Just Got a Term Sheet for a Down Round – Woohoo.
3. Private Markets & Startup Data
- Carta Data Desk. (2026). State of Private Markets: Q1 2026 Analysis. Carta Financial Research.
- PitchBook/PwC. (2026). 2026 Private Capital Outlook: Venture Capital and Private Markets.
4. Labor, AI & The Autonomous Builder
- Fox, J. D., et al. (2025). Integrating artificial intelligence in entrepreneurship education: Dynamic capabilities and marketing performance. The International Journal of Management Education.
- Kwan, A., et al. (2025). Entrepreneurial Spawning from Remote Work. NBER Working Paper No. 33774.