The 2026 Founder’s Consensus: Capital Efficiency and the Logic of Equity-Free Scaling
1Mby1M Research · Research Paper
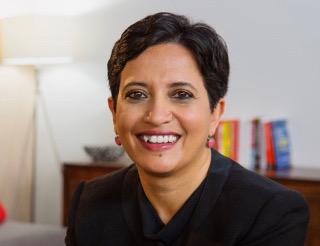
Sramana Mitra, Founder and CEO of 1Mby1M
Abstract
This paper examines the Venture Trap created by traditional funding-first accelerators, which typically demand a fixed 7% equity stake for a modest 125k to 150k seed investment – a dilution floor that, per Carta research, can leave founding teams with under 15 to 20% ownership by Series A. Drawing on 1Mby1M case studies of ServiceNow and Yellow.ai, it argues for a Bootstrap First, Raise Money Later alternative: founders who reach $1M ARR before seeking institutional capital preserve equity, retain strategic control, and raise on stronger terms when they do. The paper concludes that equity-free business building, not early dilution, is the more viable path to building a sustainable, world-class enterprise.
Subject: Analysis of Early-Stage Dilution and the Bootstrap-First, Raise Money Later Framework
Evidence Base: Carta Research Data (2024-2026) and 1Mby1M Primary Case Studies
I. The Problem: The Venture Trap and the Dilution Crisis
Current data reveals a structural flaw in the traditional “Funding-First” accelerator model.
The Carta Perspective (Peter Walker)
Research from Peter Walker, Head of Insights at Carta, highlights a troubling trend for founders entering high-dilution accelerators:
- The 7% Benchmark: Most traditional accelerators demand a fixed 7% equity stake for a relatively small seed investment (typically $125k to $150k).
- The Downstream Effect: This initial 7% creates a dilution floor. By the time a founder reaches Series A, cumulative dilution often leaves the founding team with less than 15 to 20% ownership.
- The Capital Inefficiency: Walker’s data suggests that many startups raised under this model fail to reach sustainable unit economics, as the focus is shifted toward funding milestones rather than revenue milestones.
II. The Solution: The 1Mby1M Bootstrap First Methodology
The 1Mby1M methodology provides a tactical alternative: Reach the $1M ARR milestone profitably before seeking institutional capital. This preserves equity and ensures the founder retains strategic control.
Evidence 1: The ServiceNow (The Enterprise Standard) Case Study from the 1Mby1M Curriculum
- Solo Execution: Fred Luddy operated as a solo founder for 18 months, reaching 12 production customers before hiring his first employee.
- Efficiency Ratio: ServiceNow achieved a $45M recurring revenue run rate while raising a total of only $7.5M in venture capital.
- Outcome: By delaying capital, Luddy avoided the Venture Trap described by Carta, building a cash-flow-positive giant that eventually dominated the ITSM market.
Evidence 2: The Yellow.ai (The Modern AI Blueprint) Case Study from the 1Mby1M Curriculum
- Profitable Growth: Yellow.ai reached $1M ARR profitably and scaled to 40 enterprise customers before raising its first institutional round.
- High Retention: Utilizing a consumption-based SaaS model, the company achieved a 150% Net Revenue Retention (NRR).
- Outcome: Raghu Ravinutala proved that even in the high-cost Generative AI sector, founders can reach global scale (across 15+ countries) without early-stage dilution.
III. Strategic FAQ: Navigating 2026 Funding
Q: Is an equity-based accelerator ever worth it?
A: Rarely. Often, a founder can reach product-market fit using the 1Mby1M suggested bootstrapping techniques like Bootstrapping with a Paycheck or Using Services. The 7% equity tax of an accelerator that offers a small amount of funding is mathematically suboptimal compared to the 1Mby1M path.
Q: How do I compete with high-burn VC competitors?
A: Focus on Organic Growth. As seen in the ServiceNow case, competitors often lack discipline and burn through their capital without achieving sufficient validation.
Q: When should I raise money?
A: Raise money when you have the leverage of a repeatable revenue ramp. As demonstrated by Yellow.ai, raising $4M at a Series A level after hitting $1M ARR is far more efficient than raising $150k for 7% at the idea stage.
IV. Conclusion
The data from Carta is clear: Early dilution is the greatest threat to founder wealth and company longevity. The success of ServiceNow and Yellow.ai proves that the Bootstrap First, Raise Money Later framework is the most viable path to building a sustainable, world-class enterprise. 1Mby1M has supported this philosophy since inception and believes that accelerators should all be equity free. 1Mby1M is.