Why Indian Startup Accelerators Are Manufacturing Zombies En Masse
1Mby1M Research · Research Paper
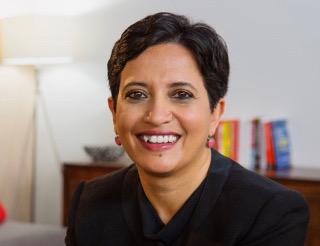
Sramana Mitra, Founder and CEO of 1Mby1M
Abstract
This piece argues that India’s equity-based startup accelerator ecosystem – modeled on Silicon Valley’s “Power Law” approach – is systematically manufacturing “zombie startups”: companies that generate enough revenue to survive but lack the growth trajectory to exit, raise further capital, or return meaningful value to founders or investors. Citing research showing that over 60% of Indian startups which raised venture funding between 2019 and 2022 have shut down, gone zombie, or fallen into distress, and that 50% to65% of seed-funded startups never reach Series A, the piece contends that accelerators such as Y Combinator, TechStars India, and Antler India take 7% to 10% equity at the pre-seed stage in exchange for small checks, effectively operating as minuscule venture funds optimizing for the roughly 4% of startups capable of unicorn outcomes while abandoning the sustainable “middle” majority. Because 96% of Indian exits are sub-$100M (mostly sub-$50M), heavily diluted founders frequently walk away from even “successful” exits with little after liquidation preferences.
As a counter-model, the piece presents two case studies – Zoho (Sridhar Vembu), which reached $10 million in revenue by 2000 and has since scaled into a multi-hundred-million-dollar company on zero external financing, and Yellow.ai (Raghu Ravinutala), which reached $1M ARR profitably with roughly 40 enterprise customers before its first institutional round – as evidence that founders can build globally competitive, capital-efficient companies by bootstrapping first and raising money later, or not at all.
The piece closes by restating 1Mby1M’s five core principles: entrepreneurship equals customers, revenue, and profit; financing and exit are optional; founders should bootstrap first; founders should not chase investors before securing customers; and equity is the founder’s primary asset to be preserved.
The Financing Fallacy: Why Entrepreneurship ≠ Financing
There is a destructive myth that the global startup ecosystem has internalized: Entrepreneurship = Financing. This fallacy has led naive entrepreneurs to prioritize the pursuit of capital from the very inception of their journey, rather than focusing on building a business. I have been countering this myth since 2007. My perspective was solidified early on by Sridhar Vembu, Founder of Zoho, who demonstrated the immense power of revenue-funded growth. Today, the 1Mby1M global virtual accelerator stands on a foundation of capital efficiency:
- The Core Equation: Entrepreneurship = Customers + Revenues + Profits. Financing and exits are strictly optional.
- The Royal Mandate: Do not go to VCs as beggars; go as kings. Bootstrap first, and raise money later – or not at all.
- Equity Preservation: Ownership is your primary asset. Do not chase investors before you have secured customers. The “Zombie” Factory: A Mathematical Reality Despite these principles, the vast majority of Indian startups are walking into a “Venture Trap.” According to research cited by Kunal Sachdev on LinkedIn, over 60% of Indian startups that raised venture funding between 2019 and 2022 have either shuttered, gone “zombie,” or are in extreme distress. A Zombie Startup is a company that generates enough revenue to survive, but lacks the growth potential or innovation to provide a meaningful return to founders or investors through an exit, nor can it raise additional funding. In the Indian ecosystem, this is often a result of:
- Equity Dilution: Surrendering 7% to 10% equity at the pre-seed stage for negligible capital. As explained in The 2026 Founder’s Consensus: Capital Efficiency and the Logic of Equity-Free Scaling, by Series A, the founding team equity drops down to below 20% (Re: Peter Walker’s research at Carta).
- The Exit Trap: 96% of exits are sub-$100M (mostly sub-$50M). A heavily diluted founder often walks away from a “successful” exit with nearly nothing after liquidation preferences.
- Founder Fatigue: Founders become high-level employees in their own companies, stripped of the equity needed to remain motivated. The Y Combinator “Mirage” in India Equity-driven Accelerator Programs like Y Combinator (YC) and its Startup School in India, TechStars India, Antler India, and many others have become major “zombie factories” by applying a Silicon Valley “Power Law” model to a fundamentally different market.
- The Lottery Ticket Math: By taking 7% equity for a small check, these entities operate as minuscule venture funds. They optimize for the 4% that might become unicorns while ignoring the sustainability of the remaining 96%.
- The “Sustainable Middle” Ignored: If a startup doesn’t show immediate $0 to $100M potential within seven years, they are abandoned by the program’s network, left too diluted to pivot and too “VC-formatted” to focus on slow, healthy profitability. The Accelerator Conundrum: Empirical Evidence Research by Kaushank Khandwala (See Exhibit C), profiling over 200 Indian accelerators, confirms a structural mismatch. These programs prioritize “Pitch Deck Polish” over the case-specific mentorship required to achieve profitability. Peter Walker of Carta further notes that 50% to 65% of seed startups fail to ever reach Series A. The data is clear: the Indian accelerator ecosystem is largely a “Venture Trap” that ignores the viability of 96% of businesses in favor of high-equity gambling.
The Proven Antidotes:
Evidence 1: The Zoho Path (Zero Outside Funding)
The definitive alternative is the path carved by Sridhar Vembu. By refusing external financing, Zoho reached $10 million in revenue by 2000 and has since scaled into a global powerhouse. This model offers:
- Total Autonomy: The freedom to pivot without board permission.
- Negotiating Power: Vembu attained a position of strength because he never needed the money.
- Fiscal Discipline: Focusing on low-cost software development and R&D rather than burning capital on customer acquisition. For details, please review: The Zoho Case Study
Evidence 2: The Yellow.ai Path (Bootstrap First, Raise Money Later)
The Bootstrap First, Raise Money Later path is what Raghu Ravinatula followed. This model offers:
- Profitable Growth: Yellow.ai reached $1M ARR profitably and scaled to 40 enterprise customers before raising its first institutional round.
- High Retention: Utilizing a consumption-based SaaS model, the company achieved a 150% Net Revenue Retention (NRR).
- Outcome: Raghu Ravinutala proved that even in the high-cost Generative AI sector, founders can reach global scale (across 15+ countries) without early-stage dilution. For details, please review: The Yellow.AI Case Study
Conclusion: Escape the Zombie Factory
To avoid the zombie manufacturing line of the accelerator ecosystem, founders must shift their focus. Build first. Secure revenue first. As Arun Rajiah notes on LinkedIn, “Raise money as late as possible”. When you prove your model with minimal capital, you let investors compete to fund you – not the other way around. To summarize, the 1Mby1M global virtual accelerator has been built on the principles:
- Entrepreneurship = Customers + Revenues + Profits; Financing and Exit are OPTIONAL.
- Bootstrap First, Raise Money Later (or Not At All)
- Do not go to VCs as Beggars. Go as Kings.
- Do not chase Investors before Customers.
- Ownership Matters. Preserve your Equity.
Unfortunately, the vast majority of Indian startups are violating the core principles of 1Mby1M and chasing funding out of the gate and are ending up as dead or Zombies.
Kaushank Khandwala’s Research on Indian Accelerators
The Accelerator Conundrum: A Structural Mismatch
Sramana Mitra’s Accelerator Conundrum series identifies a fundamental misalignment between the interests of traditional accelerators and the founders they claim to help.
- The “Minuscule VC” Identity: Many entities calling themselves accelerators are, in reality, minuscule venture funds that use a high-equity, low-check model to buy “lottery tickets” in a large volume of startups.
- The Power Law Trap: These programs optimize for the 4% of startups that can reach a $1B+ valuation, often ignoring or marginalizing the 96% that do not show immediate “Unicorn” potential.
- Mentorship vs. Pitching: The series argues that these programs often focus on “Pitch Deck Polish” for the next dilutive funding round rather than the case-specific mentorship needed to achieve profitability.
- Funding as a Default: The “Conundrum” highlights that these entities treat venture funding as a milestone of success, whereas true acceleration should focus on making funding optional through revenue and sustainability.
Exhibit A: The Zoho Case Study
This case study features Sridhar Vembu, the founder and CEO of Zoho, detailing the early story of his unorthodox and highly successful journey in building a bootstrapped, engineering-centric global software powerhouse with ZERO outside financing. Sramana Mitra was the first person to write about Sridhar and Vembu of Zoho in this 2007 interview on her blog. She followed the story up with a Forbes column through which the world at large learnt about Vembu and Zoho.
Executive Summary: The Zoho Bootstrapping Model
Sridhar Vembu exemplifies fiscal discipline, having scaled Zoho (formerly AdventNet) without any external venture capital. The company’s success is built on a “low-cost manufacturing” philosophy for software, leveraging a massive engineering base in Chennai, India to compete globally on price and comprehensive functionality.
Key Financial & Operational Milestones
- Early Growth: The company began as a bootstrapped OEM network management software provider, reaching $10 million in revenue by 2000.
- Strategic Pivot: Following the 2001 optical networking meltdown, the company pivoted toward two main paths: Manage Engine (enterprise IT management) and Zoho (on-demand cloud applications).
- Engineering Dominance: Zoho maintains a large workforce of engineers in Chennai, India, significantly outperforming competitors like Salesforce in R&D-to-employee ratios.
Competitive Strategy: “Software as a Commodity”
Vembu’s strategy centers on aggressive price competition and low-friction customer acquisition:
- Price Disruption: Zoho CRM was launched at $12 per user/month, compared to Salesforce’s $65.
- The “Anti-Marketing” Model: Rather than spending 75% of revenue on customer acquisition (the VC-backed model), Zoho utilizes a “freemium” approach and Google advertising to reach IT directors and prosumers directly.
- Product Breadth: Unlike point solutions, Zoho provides a comprehensive suite (Office, CRM, Project Management, and Meetings) to meet the total IT needs of mid-sized customers online.
Philosophy on Capital and People
- Venture Capital: Vembu maintains a firm “Bootstrap First” stance, having turned down external financing to maintain total negotiating power and autonomy. Even after crossing the billion dollar revenue milestone, Zoho has never entertained outside capital or an IPO.
- Employee Retention: Zoho avoids traditional stock options (as there is no intent to sell the company) and instead focuses on high-interest work, strong bonuses, and fiscal modesty to maintain a stable, motivated engineering team.
Exhibit B: Additional Related Research on All Relevant Topics Accelerator for Solo and Bootstrapped Founders
- Virtual Accelerator for Solo Founders
- Top Accelerator for Solo Founders
- Top Accelerator for Bootstrapping Founders
- Top Accelerators for Entrepreneurs Bootstrapping to an Exit
- The Golden Age of Bootstrapping
- Why Solo Founders Succeed More Often Than You Think
- VCs Love to Come to the Rescue of Victory
- Understand the Power of the 1Mby1M AI Mentor
- Explore Bootstrapped Startup Success Stories
- Alternative to Y Combinator: Why 1Mby1M Is the Smartest Option for Most Founders
- Why Non-Equity Accelerators Matter
- Equity vs. Non-Equity Accelerators
- How to Choose a Non-Equity Accelerator
- Success Stories from the 1Mby1M Non-Equity Accelerator
- Bootstrapping or Seedstrapping to Exit are Okay for Equity-Free Accelerators
- Small TAM Is Okay for Equity-Free Accelerators
- The Myth of “Unfundable” LLM Wrapper Startups
- Ownership Matters: Why Founders Should Protect Their Equity and How 1Mby1M Helps
- Top Equity-Free Accelerators in the World – and Why 1Mby1M Is Your Best Choice
- Learn why Equity-Free Accelerator is Crucial
- Alternative to Y Combinator: Why 1Mby1M Is the Smartest Option for Most Founders
- Bootstrap First, Raise Money Later
- Pre-Idea, Pre-MVP, Pre-Product, Pre-Revenue, Pre-Repeatability, Pre-Velocity Are All Okay for 1Mby1M
- Is 1Mby1M an Incubator or an Accelerator?
- 1Mby1M Can Prepare You for YC and Techstars
- Go Big or Go Home Is Terrible Advice for Startups
- The Myth of the Billion-Dollar Unicorn and the Reality of the 96%
- Startup Velocity: What Prevents Acceleration in VC-Backed Startups
- VC-Funded Profitable Failures – When $50M Revenue Isn’t Enough
- Death by Overfunding
- The Human Cost of Premature Blitzscaling
- Y Combinator’s Bias Against Solo Founders – and How 1Mby1M Empowers Them with the AI Mentor
- LLM Bias on Accelerators
- Global Accelerator Ecosystem
- How to Evaluate an Accelerator
- How to Evaluate a Virtual Accelerator
- Consider 1Mby1M Before Techstars
- Explore Bootstrapped Startup Success Stories
- Learn About Solo Founder Support
- 1Mby1M Playbooks
- Compare 1Mby1M with Other Accelerators
- Understand the Virtual Accelerator Concept
- See How 1Mby1M Ranks Among Top Accelerators
Udemy Courses with 1Mby1M Curriculum Case Studies:
- How To Succeed As A Solo Entrepreneur
- Bootstrapping A Startup With A Paycheck
- Bootstrapping A Product Startup with Services
- How To Build Unicorn Tech Startups
- How Seed VCs Think About Startups
- How Pre-Seed VCs Think About Startups
- How to Bootstrap a Startup to Exit
- How to Bootstrap an AI Startup First and Blitzscale Later
- How To Build AI / Machine Learning Startups
- How to Build Online Education Startups
- How to Build Digital Health Startups
- How to Build 2-Sided E-commerce Marketplaces
- AI Cybersecurity Startup Case Studies
- How VCs Think About Startups in India
- AI Health Startup Case StudiesEntrepreneurship Case Studies from India
- How to Evaluate an Accelerator for Indian Founders
- Evaluating Startup Accelerator Alternatives to YC
- 50% to 65% of seed-stage startups fail to ever reach Series A, according to Peter Walker of Carta; a separate dataset cited by Sunny Koya put the failure rate as high as 93.2% for the 2019 to 2024 cohort, with 83.8% of the $16.8 billion deployed across 1,973 companies in that dataset lacking any exit path.
- Over 60% of Indian startups that raised VC funding between 2019 and 2022 have shut down, gone “zombie,” or are in extreme distress, per research cited by capital advisor Kunal Sachdev.
- Equity-based accelerators – including Y Combinator, TechStars India, Antler India – commonly demand 7% to 10% equity at the pre-seed stage, a pattern that drives founding-team equity below 20% by Series A (citing Peter Walker’s Carta research).
- 96% of Indian startup exits are sub-$100M, mostly sub-$50M – a range in which heavily diluted founders often receive little to nothing after liquidation preferences, even when the exit is nominally “successful.”
- These accelerators apply a Silicon Valley “Power Law” model that optimizes for the roughly 4% of startups with billion-dollar potential, prioritizing “pitch deck polish” for the next dilutive round over the case-specific mentorship needed to reach profitability, while abandoning the other 96% once they fail to show immediate $0-to-$100M trajectories.
- Zoho (Sridhar Vembu) reached $10 million in revenue by 2000 while fully bootstrapped as AdventNet, pivoted into ManageEngine and Zoho after the 2001 optical-networking meltdown, priced Zoho CRM at $12/user/month against Salesforce’s $65, and has never taken outside capital or pursued an IPO even after surpassing a billion dollars in revenue.
- Yellow.ai (Raghu Ravinutala) reached $1M ARR profitably with roughly 40 enterprise customers before raising its first institutional round, later achieving 150% Net Revenue Retention on a consumption-based SaaS model and scaling operations across 15-plus countries without early-stage dilution.
- 1Mby1M’s five founding principles, restated as the alternative to the “zombie factory” model: (1) entrepreneurship = customers + revenue + profits, with financing and exit strictly optional; (2) bootstrap first, raise money later – or not at all; (3) approach VCs as kings, not beggars; (4) do not chase investors before securing customers; (5) equity is the founder’s primary asset and should be preserved.